NTPC Business Model: Regulated Returns, Capacity and the Renewable Pivot
How NTPC earns from power generation, why availability and regulation matter, and how coal cash flows fund a much larger renewable build-out.
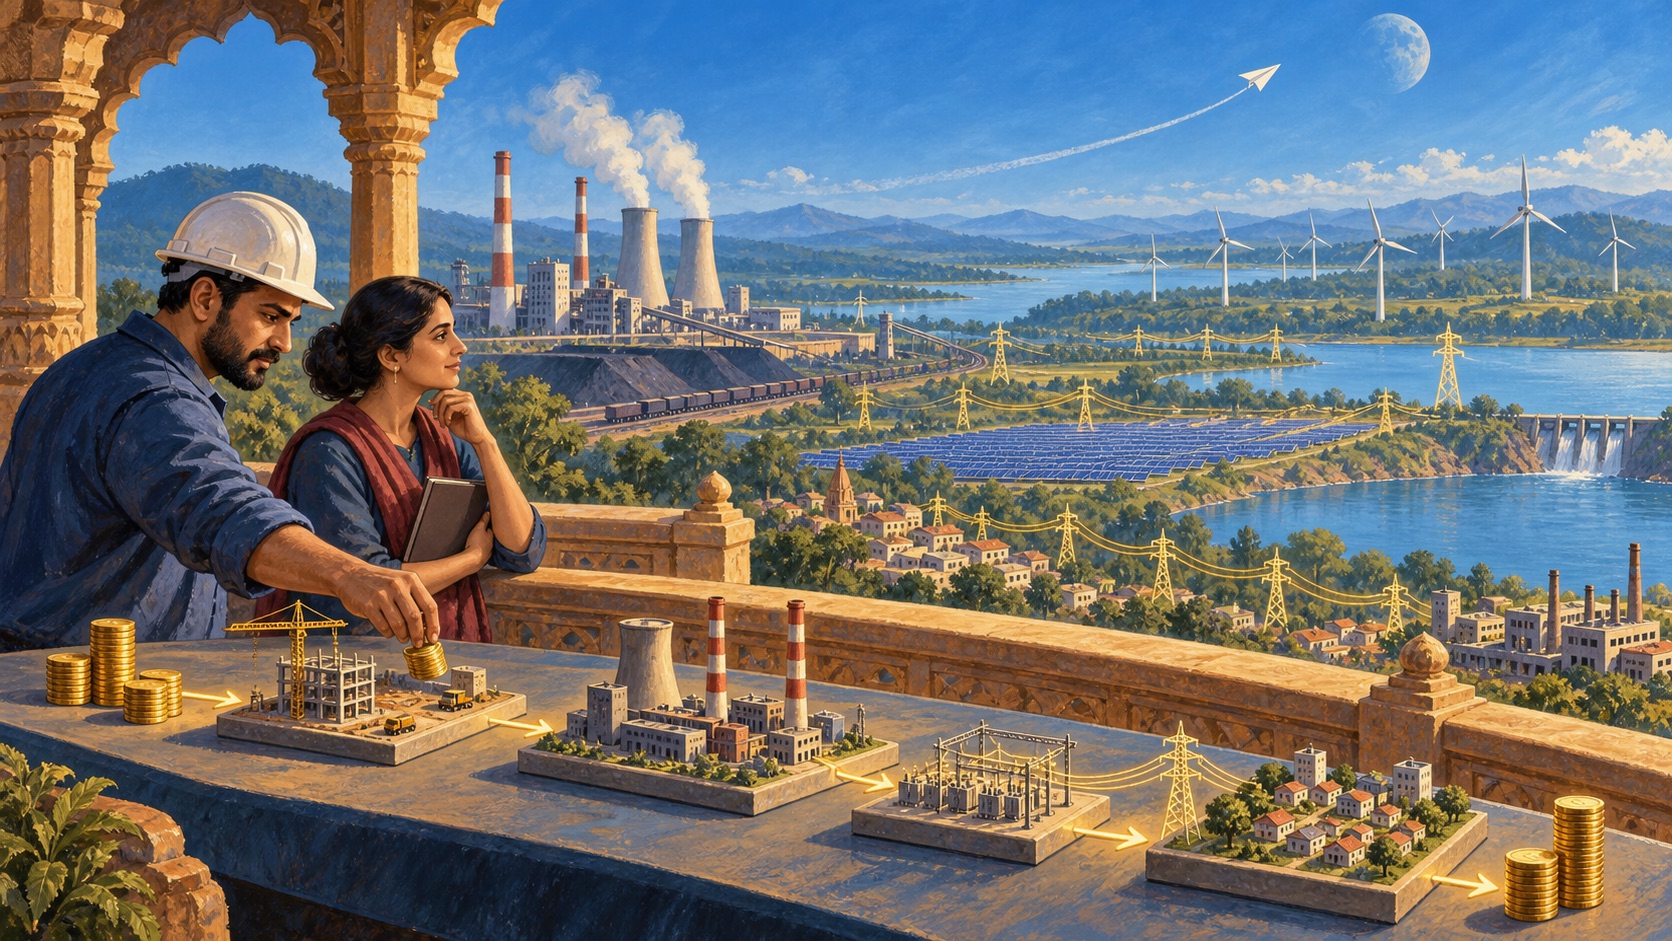
NTPC sells electricity, but its business model is not simply “units generated multiplied by market price.” Much of its fleet operates under a regulated framework designed to recover eligible costs and earn a return on the equity invested in approved projects, subject to operating norms.
That makes NTPC a construction programme, an operating utility and a financing machine at once. It must build huge assets on time, keep them available, secure fuel, bill customers and collect cash. It is now attempting the same at much larger scale across renewable energy.
The regulated engine
A thermal power station has heavy upfront capital cost and a long useful life. Tariffs broadly contain two economic buckets:
- Fixed charges, which recover eligible fixed costs and provide a regulated return when availability and other conditions are met.
- Energy charges, which recover fuel-related costs based on regulation and operating parameters.
The exact tariff is more complex than this summary, but the distinction explains why generation volume is not the only operating measure. A station can be available even when the grid does not schedule it at full output. Availability protects fixed-cost recovery; PLF shows actual utilisation.
Capacity is the asset base
NTPC’s filing-linked Q1 FY27 presentation recorded 90.9 GW of operating group capacity and 35.7 GW under construction. Coal remained the largest component. The group also reported 12 GW of operational renewable capacity and a visible renewable pipeline of about 30 GW.
The economic bridge is:
Capital invested → project commissioned → commercial operation → regulated or contracted revenue → cash collection
Until commercial operation, a project consumes capital without contributing a full period of operating earnings. Delays can raise financing cost and postpone returns. Commissioning is therefore more important than announcements alone.
Availability and PLF answer different questions
PLF is actual generation divided by theoretical maximum generation. Availability is whether the plant was capable of operating.
NTPC’s official Q1 FY27 release said its coal stations achieved 76.71% PLF, above the 70.32% reported for the rest of India’s coal fleet. Its broader FY26 presentation recorded more than 85% average declared capacity.
High PLF can reflect strong electricity demand and competitive dispatch. High availability reflects maintenance and operational readiness. An analyst should track both, as well as the gap between them.
Fuel security protects availability and working capital
Coal availability, quality and transport affect generation and cost. NTPC reported long-term fuel tie-ups covering around 110% of requirements, approximately 18% of coal requirements supplied from captive mines in FY26, and 60% of coal capacity connected through merry-go-round rail systems.
Captive coal is not automatically “free.” Mining requires capital and operating cost. The value is greater control over supply and logistics. Fuel analysis should connect volume, landed cost, inventory and regulatory pass-through rather than celebrating production in isolation.
The renewable pivot changes the economics
Renewable projects have no coal bill, but they still require land, grid connections, equipment, financing and contracted offtake. Returns depend on auction tariffs, equipment cost, capacity factor, curtailment, project execution and the cost of capital.
NTPC has set out a target of 60 GW of renewable capacity by FY32 and 136 GW by FY37. Those are strategic targets, not current earning assets. The research job is to build a conversion ladder:
- Announced target
- Pipeline
- Awarded project
- Under construction
- Commissioned capacity
- Commercial operation and revenue
- Cash return on invested capital
The gap between each rung is where execution risk lives.
Q1 FY27 in the accounts
Altys’ official-XBRL history shows:
| Metric | Q1 FY26 | Q1 FY27 | Change |
|---|---|---|---|
| Revenue from operations | ₹47,065 cr | ₹50,741 cr | +7.8% |
| EBITDA as filed in XBRL | ₹12,580 cr | ₹16,231 cr | +29.0% |
| PAT attributable to owners | ₹6,011 cr | ₹6,721 cr | +11.8% |
NTPC’s official release reported group PAT of ₹6,896 crore; the Altys table uses profit attributable to owners to maintain a consistent owner-earnings basis. That basis difference should be explicit, not “fixed” by choosing whichever number looks better.
For FY26, Altys’ exchange-only trailing ratios show consolidated ROCE of 8.3% and ROE of 14.0%. A regulated utility can sustain a lower ROCE than an asset-light company because earnings are tied to a large approved asset base and long-lived contracts. The comparison must match the business model.
Receivables can turn accounting profit into financing
Utilities sell to distribution companies that may pay with a lag. When receivables rise, NTPC effectively finances its customers. The company reported FY26 trade receivables of 31 days, but this should be monitored continuously and by counterparty quality.
Cash conversion matters because the capex programme is enormous. NTPC reported FY26 group capex of roughly ₹55,986 crore. A gap between profit and cash collection can increase borrowing just as new projects demand funding.
What can go wrong
- Project delays and cost overruns
- Fuel shortage, logistics disruption or weak plant availability
- Receivable stress at distribution companies
- Regulatory changes or disallowance of costs
- Renewable auction tariffs that leave little room for execution error
- Rapid capex growth weakening balance-sheet flexibility
- Treating target capacity as commissioned capacity
The research takeaway
NTPC’s existing thermal fleet is a regulated cash-flow engine supporting one of India’s largest power-capacity build-outs. The opportunity is visible, but the economics live in conversion: from capex to commercial operation, from availability to tariff recovery, and from billed revenue to collected cash.
Altys helps keep those stages in one monitored record—financials, operating KPIs, management targets and actual outcomes—so every quarter updates the same investment thesis rather than starting a fresh spreadsheet.
Data note
Financial figures use Altys’ point-in-time warehouse and official NTPC disclosures available through 12 September 2026. Quarterly figures are consolidated and rounded. Capacity targets and pipeline figures are management disclosures, not forecasts by Altys.
This article is educational. Altys Labs is not a registered research analyst or investment adviser, and nothing here is a recommendation to buy, sell or hold any security.
Frequently asked questions
How does NTPC make money?
NTPC builds and operates power stations and sells electricity, mainly through long-term arrangements. For regulated assets, tariffs are designed to recover eligible costs and provide a return when operating and availability conditions are met.
What is plant load factor?
Plant load factor, or PLF, measures actual generation relative to the maximum possible generation over a period. It shows how intensively a plant was used.
Why does availability matter for NTPC?
For regulated power stations, a meaningful part of fixed-cost recovery depends on the plant being available to generate, even if the buyer does not always schedule all available power.
What should analysts track for NTPC?
Installed and commercial capacity, availability, PLF, regulated equity, fuel security, receivables, capex, project commissioning and renewable capacity economics.